Table of Contents
Most people who start a trucking company have already spent years driving for someone else. The reason to run under your own authority usually comes down to keeping more of what each load pays.
On paper, how to start a trucking company is a short list. You register the business, file for a USDOT number and operating authority, get insured, and start hauling. The steps depend on each other, and the order they happen in is where new carriers lose time and money.
The authority does not go active until your insurer files proof of coverage with FMCSA. Many brokers will not load a carrier whose authority has no age on it. Payment for a delivered load commonly arrives 30 to 45 days after delivery. Since 2026, the federal filing itself runs through a new FMCSA system called Motus, so older guides that walk through the Unified Registration System describe screens that are gone.
This guide walks through each stage in the order it happens, including the delays that show up between them.
Quick Overview
Starting a trucking company takes a registered business entity, a USDOT number, operating authority (the MC number), liability and cargo insurance on file with FMCSA, a BOC-3, and the state and federal registrations that keep a truck legal on the road. All federal registration now runs through FMCSA’s Motus system.
When the filings overlap, active authority typically takes about 4 to 6 weeks from the application. Done one after another, it takes longer. Broker setup and the first payment come after that, so the business needs cash to carry it well past the day the authority goes active.
Running under your own authority is 1 of 3 common ways to own and operate a truck. The other 2 are leasing on to a carrier and running a lease purchase. The trade-offs between all 3 are covered in the guide to becoming an owner operator, and this article assumes you have already chosen your own authority.
What a Trucking Company Actually Consists Of
A trucking company is a registered business with federal operating authority, insurance on file with FMCSA, and the ability to contract with freight brokers or shippers to move loads.
A 1-truck operation has 5 working parts:
- A legal business entity, usually an LLC
- A USDOT number, the federal identification number for the carrier
- Operating authority for interstate freight for hire
- Liability and cargo insurance
- At least 1 commercial vehicle
Each part feeds the next. FMCSA publishes the authority application in the FMCSA Register, and your insurer then has a deadline to file proof of coverage. FMCSA activates the authority once the insurance filing and the BOC-3 are on file and the protest window has closed. Brokers then pull these records before they put a carrier on a load, and a gap in any one of them stops the setup.
A delay at the first step pushes every later step back, including the first payment.
Running your numbers is one side of the business. Getting paid is another. My free 16-video series breaks down what factoring really costs:
Registering the Business Entity
Most new carriers register as an LLC. The LLC separates personal assets from the trucking business. Some carriers run as sole proprietors, which leaves personal assets exposed to claims filed against the carrier.
The LLC is filed with the state where the carrier will be based. Filing fees and processing times vary by state, so check your state’s business filing office for the current fee before you budget it.
With the LLC registered, the next step is an Employer Identification Number (EIN) from the IRS. You need the EIN for tax filings, for a business bank account, and for the FMCSA application. Open the business bank account at this stage so every load payment lands in the business from the first invoice.
Keep the legal name and address identical across the LLC filing, the EIN and the Motus application. Brokers and insurers compare these records against each other, and a name or address that doesn’t match has to be corrected before a setup moves forward.
Choosing a State of Registration
The state where you register affects annual reporting fees, franchise taxes and the filings you owe each year. Most carriers register in their home state. A carrier that registers its LLC in a different state still has to register as a foreign entity in any state where it keeps a physical office or terminal, which adds a second set of fees and reports to keep current.
Getting Your DOT and MC Numbers
Registration Now Runs Through Motus
FMCSA registration now runs through Motus, which FMCSA calls its new registration system on its Insurance Filing Requirements page. Motus replaced the Unified Registration System in 2026. If a checklist, course or video tells you to log in to URS, it was made before the switch and describes the old system.
Motus handles both the USDOT number and the operating authority application, so both filings start in the same place.
The USDOT Number
The USDOT number is the federal identification number FMCSA assigns to a carrier. FMCSA uses it to track the carrier’s safety record, inspection results, compliance reviews and crash data.
The USDOT number identifies the carrier. The right to haul regulated freight for hire across state lines comes from a separate grant, operating authority.
MC Operating Authority
Operating authority, identified by the MC number, is the federal grant that lets a company haul freight for compensation in interstate commerce. Without it, a carrier cannot legally take loads from brokers or shippers that cross state lines.
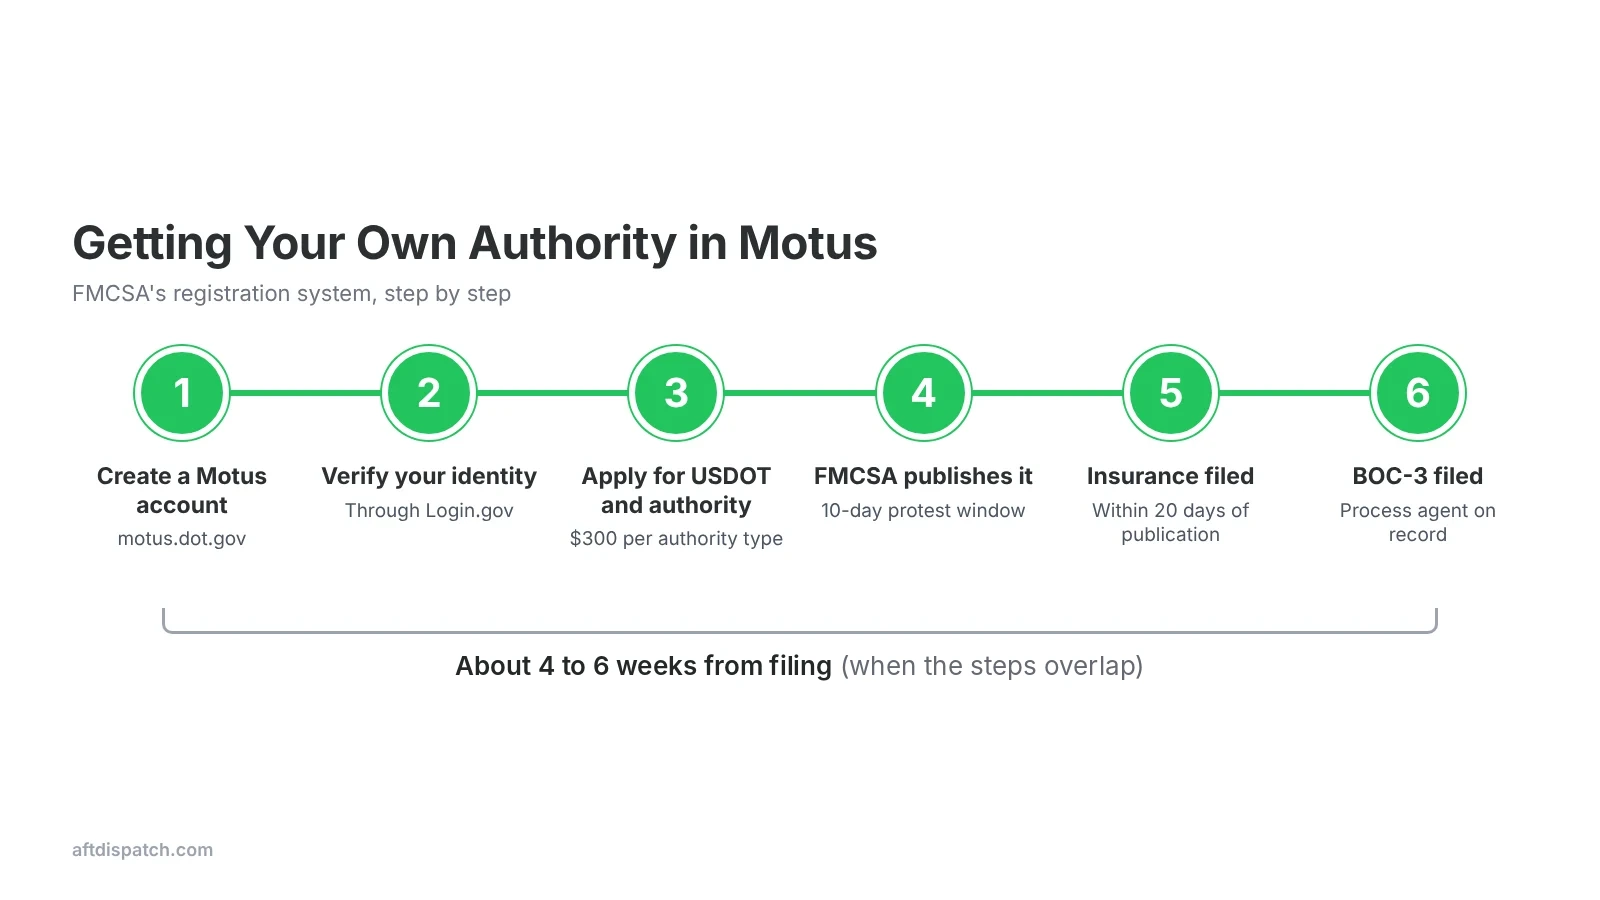
The authority application is filed in Motus alongside the USDOT number. The filing fee is $300 for each type of authority, and it is non-refundable (otrucking FMCSA registration guide). Most new carriers haul general freight under common carrier authority and pay $300. A carrier that needs 2 types of authority pays $600.
After filing, the sequence runs like this:
- FMCSA publishes the application in the FMCSA Register.
- A 10-day protest window opens from the publication date (49 CFR 365.203T).
- Your insurer has 20 days from publication to file proof of coverage with FMCSA. Miss that deadline and the application is dismissed unless you comply within 60 days (FMCSA).
- Your BOC-3 has to be on file.
- With the protest window closed and the filings accepted, the authority goes active.
The 20-day clock is the reason to line up insurance quotes before you file. A carrier that starts shopping for a policy after publication spends the protest window collecting quotes, and an insurer that is slow to bind can push the filing up against day 20.
When the steps overlap (insurance quoted before filing, BOC-3 filed right after the application), active authority typically takes about 4 to 6 weeks from the application (otrucking). When each step waits for the one before it, the process runs longer. Those are typical ranges, and FMCSA processing and insurer response times can move them in either direction.
During this window the carrier cannot haul under its own authority. It can bind insurance, join a drug testing consortium, set up the ELD, and prepare the documents brokers will ask for.
The MC Number May Be Phased Out
FMCSA may phase out MC numbers and identify carriers by USDOT number alone. No date has been set. FMCSA’s FAQ on the MC number change addresses whether existing MC numbers would be replaced. Until a change takes effect, brokers still ask for the MC number, so keep it on your setup documents and invoices.
How DOT and MC Numbers Work Together
The USDOT number places the carrier in the federal safety system. The MC number shows the carrier is authorized to operate for hire. Brokers check both. A carrier with a USDOT number and no active authority fails broker compliance screening at the first check.
Both records show up in FMCSA’s public SAFER system, which brokers and shippers use to verify carrier credentials before they assign a load.
This is one piece of running a tighter operation. If getting paid is the piece you’re working through, the free 16-video factoring series covers what it actually costs:
Insurance Requirements for New Carriers
Liability Insurance
Federal rules set a minimum of $750,000 in liability coverage for for-hire carriers hauling non-hazardous freight in vehicles of 10,001 pounds or more (FMCSA Insurance Filing Requirements). Many brokers require $1,000,000 before they will put a carrier on a load, so a carrier insured at the federal minimum gets turned away by those brokers.
Liability insurance pays for damage the truck causes to other vehicles, property and people. On a new authority, $1,000,000 in primary liability alone often runs about $10,000 or more a year (Overdrive insurance guide).
Cargo Insurance
Cargo insurance covers the value of the freight on the truck. Brokers set their own cargo minimums, and some commodities carry higher limits than general dry freight. Check the cargo limit in the setup requirements of the brokers you plan to work with before you bind, since raising a limit after the policy is written means another round with the insurer.
What the Full Insurance Bill Looks Like
Primary liability is the largest single coverage, and it is only part of the bill. Physical damage and cargo coverage stack on top of it. All in, insurance on a new authority often runs $20,000 or more a year (Overdrive). For most new carriers, insurance is the largest cost of opening the business after the truck itself.
Why Insurance Is Expensive for New Authorities
Insurers price risk from a carrier’s history. A new authority has no inspection history and no claims data to price from. To the underwriter, it is an unknown risk, and the premium reflects that.
Premiums can come down at renewal once the carrier has a clean record behind it. Some insurance agents specialize in new authorities and place them with markets that will write new ventures, sometimes with higher deductibles or tighter coverage terms in exchange for a lower premium. Read those terms before you bind, since a higher deductible is cash the business has to have on hand after a claim.
BOC-3 Filing
A BOC-3 names a process agent in each state, a person or company that accepts legal papers on the carrier’s behalf. FMCSA needs it on file before it activates the authority.
Process agent companies file the BOC-3 for you, and many insurance agents can arrange it. File it early, right after the authority application, so it runs alongside the 10-day protest window instead of starting after it.
Startup Costs for a Trucking Company
Startup cost depends mostly on the truck and on insurance. The federal and state registration fees are small next to either one. The table lists the figures that are fixed or published. The rest depends on your state, your truck and your providers.
| Expense | Cost |
|---|---|
| Operating authority filing fee (Motus) | $300 for each type of authority, non-refundable |
| Insurance on a new authority, all coverages | Often $20,000 or more a year |
| $1,000,000 primary liability alone | About $10,000 or more a year |
| UCR, 0 to 2 vehicles | $46 for 2026, $55 for 2027 |
| Form 2290 heavy vehicle use tax | Up to $550 a year for a truck over 75,000 lbs |
| IRP apportioned plates | Varies by state and truck weight |
| LLC filing, BOC-3, ELD, drug testing consortium | Varies by state and provider |
Sources: otrucking (authority fee), Overdrive (insurance), UCR Plan (UCR), IRS (Form 2290).
These figures leave out the truck. A purchased truck, a lease and a lease purchase each put a different payment on the business, and that payment belongs in your cost per mile from the first load.
Several of these costs recur. UCR and the 2290 come due every year, and IRP plates renew on your base state’s schedule. Budget them as yearly running costs of the business.
Startup costs are what it takes to open. What it costs to get paid is a separate bill, and my free 16-video series walks through it, fees and traps included:
How New Trucking Companies Actually Get Their First Loads
Active authority makes a carrier legal to haul. Getting loaded takes a broker who will approve the setup, and that approval is the step new carriers plan for least.
Know Your Numbers Before the First Broker Call
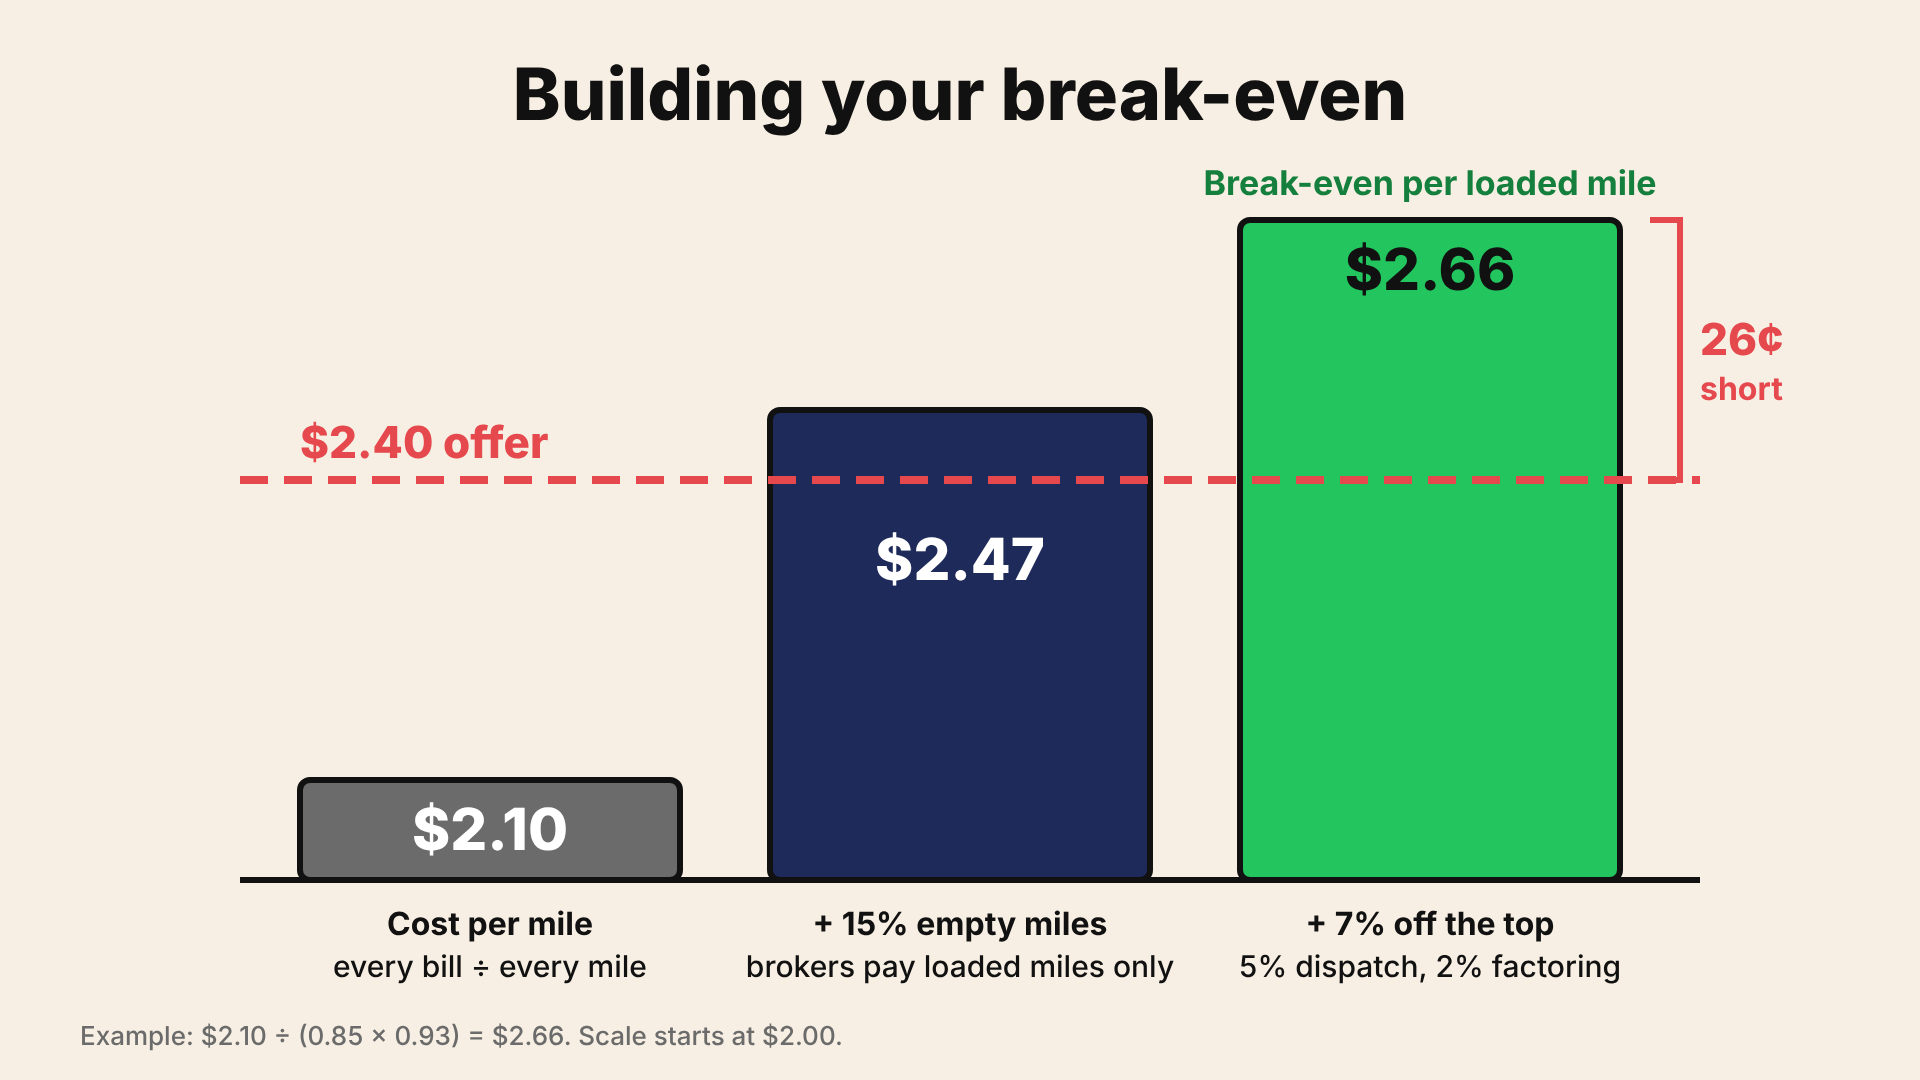
Work out 2 numbers before you call a broker. The first is your break-even per loaded mile, the rate below which a load loses money once empty miles and fees are counted. That is the floor. The second is your target, the rate that also covers what you pay yourself.
An offer under the floor gets a counter or a pass. An offer between the floor and the target gets weighed against what else is on the board. The trucking cost per mile breakdown walks through the inputs. Trucking Super Calc, AFT Dispatch’s free trucking calculator app for Android, works out your break-even and pay-yourself rates from your own costs.
Load Boards
Load boards are online platforms where brokers post loads and carriers search for freight. DAT, Truckstop and Direct Freight are among the most used. New carriers usually start on load boards because they have no broker relationships yet.
Most load board freight is spot freight that a broker needs moved soon. Spot rates move with the market and often sit below contract rates, which is one more reason to have the floor worked out before the first call.
What Brokers Check During Setup
Before a broker tenders a load, the carrier goes through setup. Many brokers run it through an onboarding platform such as Highway, RMIS or MyCarrierPackets. The broker checks your authority status, insurance coverage and safety record, and expects these documents:
- A W-9 for the business
- A certificate of insurance (COI) that names the broker
- Your USDOT and MC numbers
Your insurance agent issues the COI, and every new broker needs its own. Ask your agent how fast they turn around certificate requests, since a slow COI can cost you a load that was ready to book.
Many brokers also want the authority to have some age before they load a carrier. The minimum differs from broker to broker, and some will turn down a brand new authority however clean the driver’s record is.
Why Broker Vetting Got Stricter in 2026
On May 14, 2026, the Supreme Court ruled 9 to 0 in Montgomery v. Caribe Transport II that brokers can be sued under state law for carelessly selecting an unsafe carrier (Overdrive). Brokers now vet carriers harder.
A new carrier has the least record to show. With no inspection history behind you, what a broker can check is your paperwork: documents that match each other, insurance at the broker’s limits, and a testing program already in place. Have those ready before the first call.
Ask the Right Question on the Call
Opening every call with “I’m new” invites a no before the load is discussed. Ask instead whether the broker works with new authorities. A broker who does will tell you what it needs, and the call moves to setup. A no ends the call before you spend time on a packet that would have been rejected.
A typical sequence on a load board call:
- Confirm the load fits your truck: pickup, delivery, weight and equipment.
- Ask whether the broker works with new authorities.
- Get the rate and check it against your floor.
- Ask which onboarding platform the broker uses and start the setup.
- Send your insurance agent the COI request naming that broker.
Each load delivered on time with clean paperwork adds to the record the next broker checks. Keep a list of the brokers who approved you early and offer them your truck again while the authority ages.
Direct Shipper Relationships
Some carriers contract directly with shippers and skip the broker. This works best in local or regional operations, where the carrier can visit warehouses and distribution centers in person. Direct freight usually pays better because no broker margin comes out of the rate. Building those relationships takes time running the same area consistently, so it rarely covers a new carrier’s first loads.
The full process of finding freight is covered in the guide on how to get loads for trucks.
The Cash Flow Problem Most New Carriers Encounter
Brokers do not pay at delivery. Broker payment terms commonly run 30 to 45 days. During that wait, fuel, insurance, the truck payment and your living costs still come due every week.
A First-Load Timeline
Here is how that plays out, as a worked example counted from the week the authority goes active:
- Week 3: first load booked, after broker setups clear
- Week 4: load delivered, invoice sent
- Around week 8 to 10: first broker payment arrives
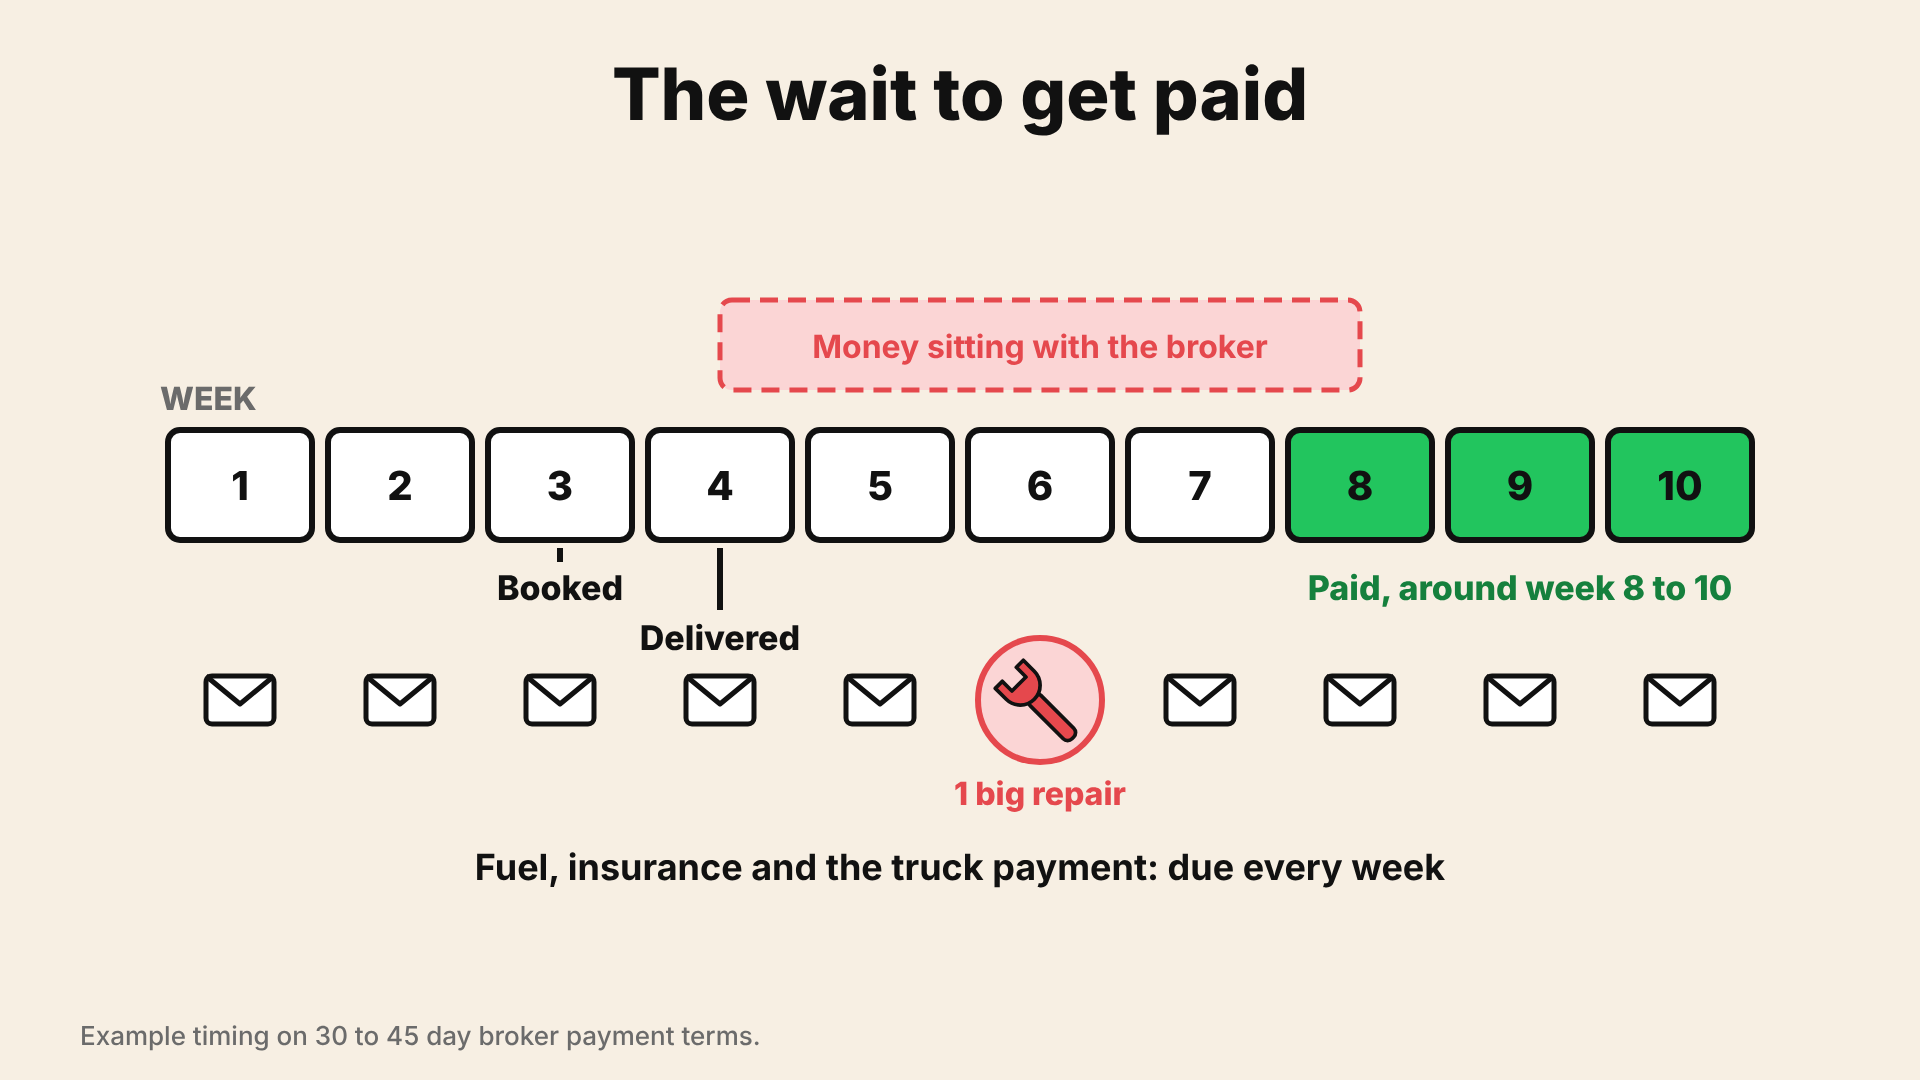
From the day the authority goes active to the first payment, the carrier runs about 2 months on its own cash. Every load booked in those weeks spends fuel money now against a payment that arrives 30 to 45 days later.
Why Factoring Becomes Common
Freight factoring closes that gap by selling the invoice. The factoring company advances most of the invoice amount soon after delivery, collects the full amount from the broker on the broker’s terms, and keeps a fee. Many new carriers factor during their first months while they build a cash reserve. Some stop once they can carry 30 to 45 days of receivables on their own.
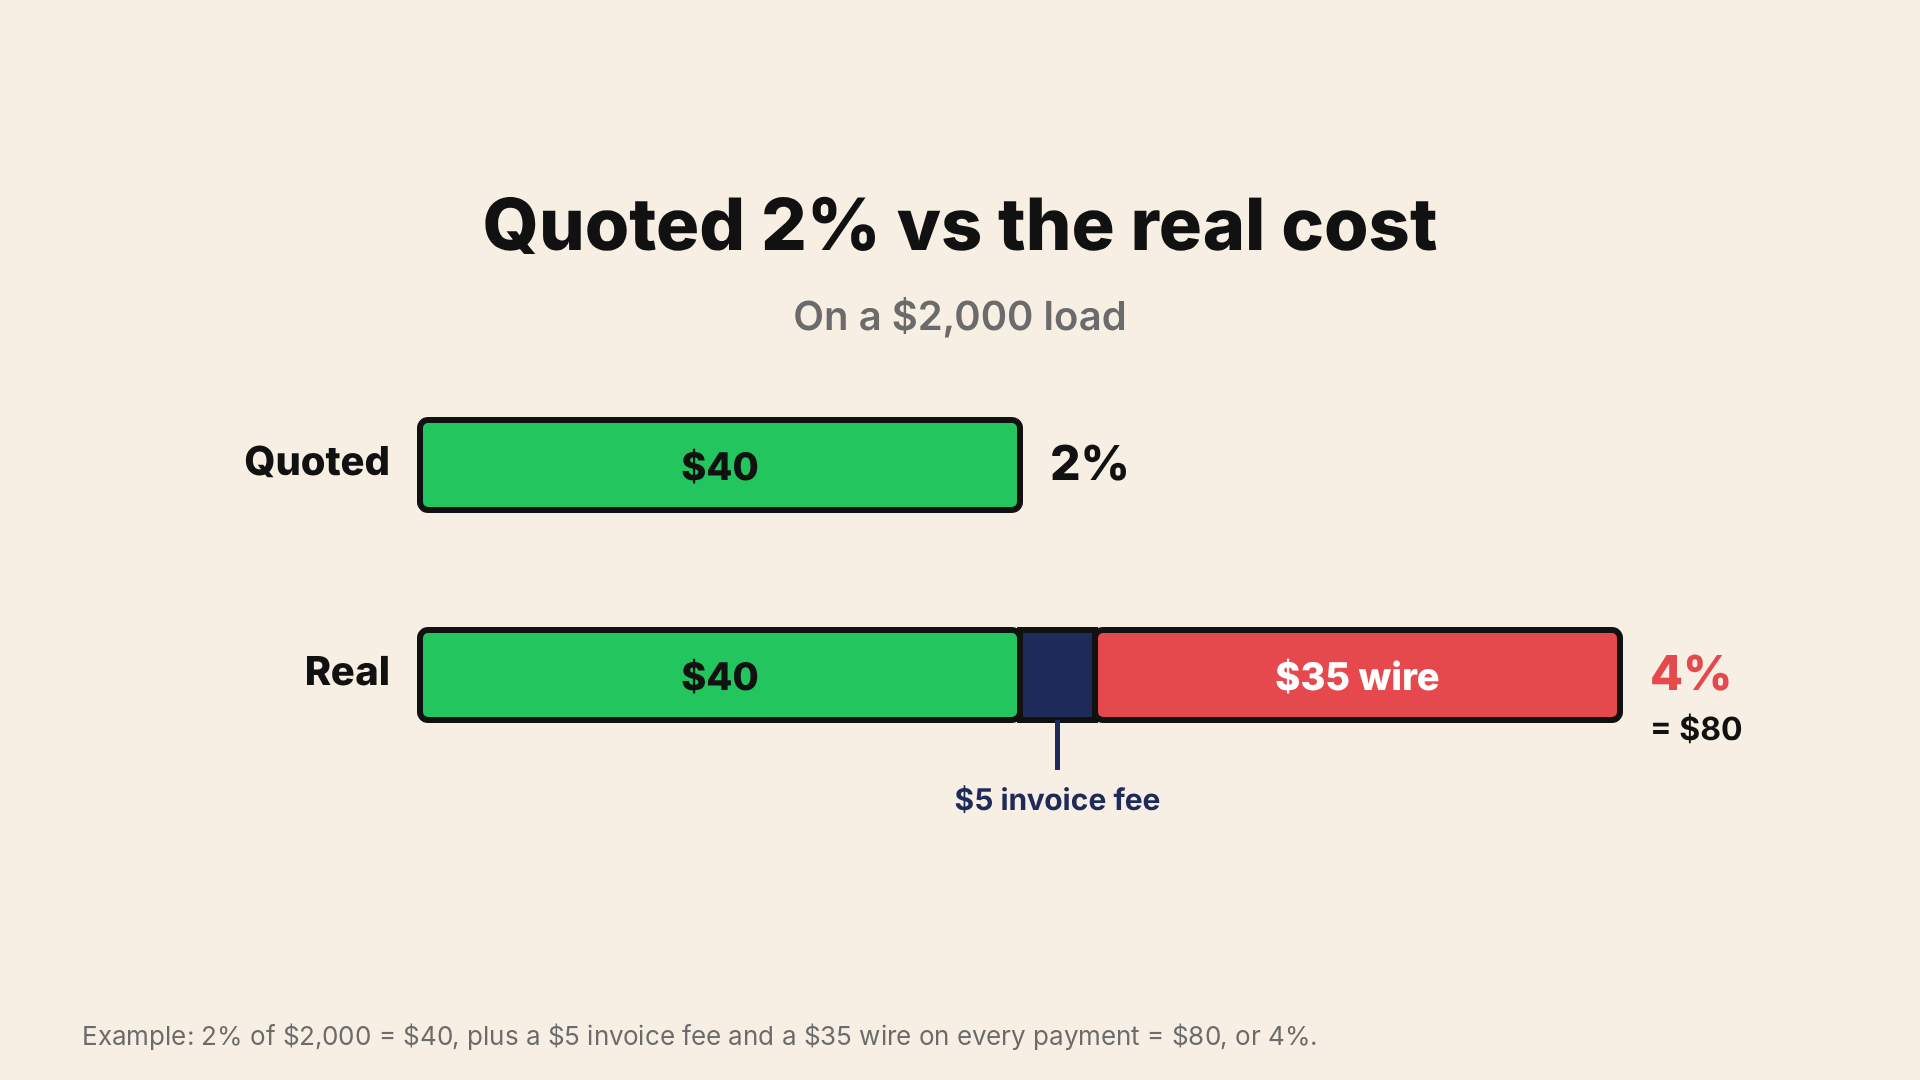
The fee is the price of not waiting. The real cost depends on the quoted rate plus any flat fees per invoice, so compare the total charge on a typical load against the headline percentage. The breakdown of why owner operators run out of cash shows how the wait to get paid stacks on top of the truck’s costs.
Covering the Gap Before the First Payment
Before the first load, add up what the business spends in a month: fuel, insurance, the truck payment, maintenance, tolls and your own living costs. Hold enough cash to cover that from the week the authority goes active until the first payment arrives, about 2 months in the worked example above. A carrier that starts with enough for the first couple of weeks of fuel runs dry before the first broker pays.
The factoring series covers this and 15 other mechanisms that affect carriers in real operations:
Compliance Requirements After Authority Is Active
Active authority starts the compliance clock. These requirements decide whether the carrier stays in operation through its first 18 months.
The New Entrant Safety Assurance Program
New carriers enter FMCSA’s New Entrant Safety Assurance Program. FMCSA monitors the carrier for 18 months and conducts a safety audit within the first 12. Some findings are automatic failures:
- No drug and alcohol testing program
- No required insurance
- No hours of service records
Set up each of these before the first load. The audit looks back at records you should already have, so a program started the week before the audit leaves months of missing records behind it.
Drug and Alcohol Testing
An owner operator who drives their own truck still needs a testing program. Owner operators must be in a consortium’s random testing pool (FMCSA, owner operator testing). Join the consortium before the first load so you are in the pool from day 1.
UCR Registration
Unified Carrier Registration (UCR) is a yearly registration for interstate carriers, with fees set by fleet size. For 0 to 2 vehicles, the fee is $46 for 2026 and $55 for 2027 (UCR fee brackets).
IFTA Fuel Tax Reporting
The International Fuel Tax Agreement (IFTA) applies to carriers that run in more than 1 state. Each quarter, the carrier reports miles driven and fuel bought in each state. Some states are owed tax, and others issue credits. IFTA decals go on the truck. Keeping fuel receipts and state miles from the first trip is far easier than rebuilding them at the end of the quarter.
IRP Plates
The International Registration Plan (IRP) lets a truck based in 1 state run in all member jurisdictions on apportioned plates. The cost depends on your base state and the truck’s weight, so there is no single national price. Get the figure from your base state’s IRP office before you budget it.
Form 2290
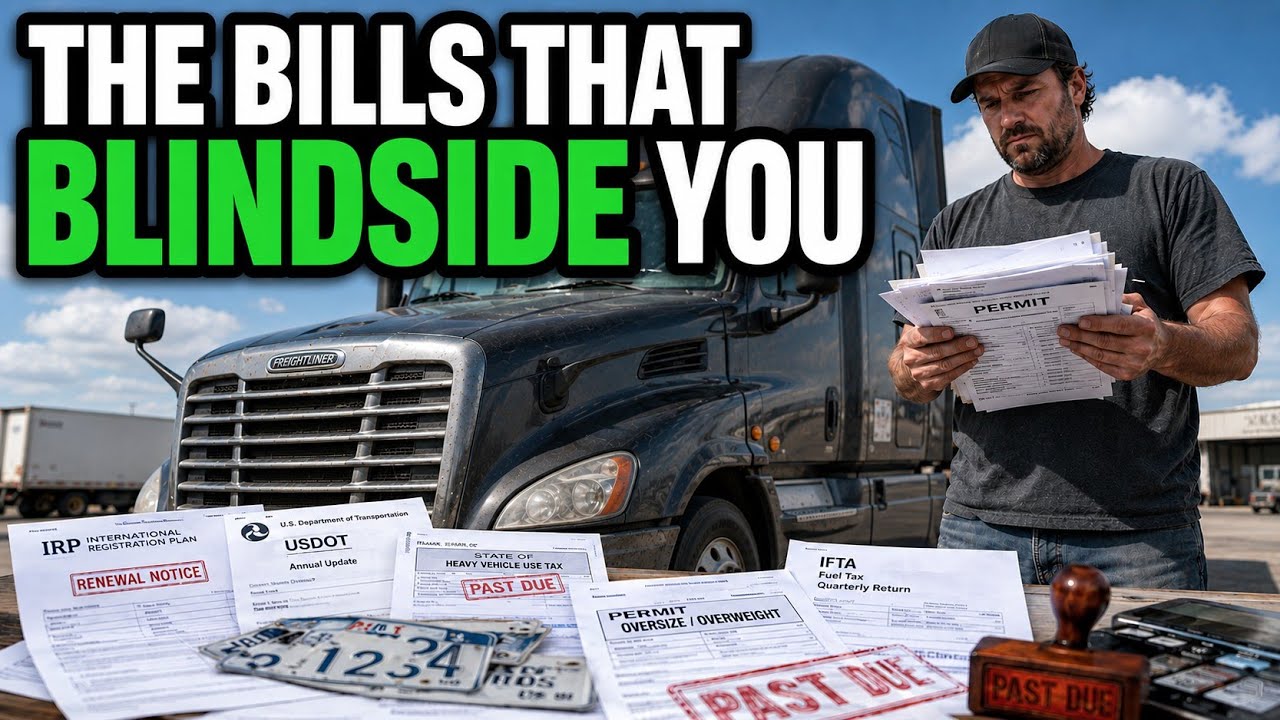
Form 2290 is the federal heavy vehicle use tax, filed with the IRS. For a truck over 75,000 pounds, it runs up to $550 a year (IRS, About Form 2290). The yearly cycle of UCR, IFTA, IRP and the 2290 is covered in more detail in keeping your authority legal.
ELDs
Most interstate commercial vehicles must run an electronic logging device (ELD), which records hours of service automatically and has to be available for inspection. The ELD also produces the hours of service records the new entrant audit checks.
Common Mistakes New Trucking Companies Make
Underestimating Cash Reserves
A carrier that starts with enough for the first week of fuel is out of cash before the first broker pays. With payment arriving around week 8 to 10 in the worked example, the reserve has to carry about 2 months of costs. Count the reserve before you file, since the filing fee and the first insurance payment come out of the same account.
Not Planning for Broker Screening
New carriers often expect loads the day the authority goes active. Many brokers want some authority age first, and every broker runs a setup before the first tender. Plan for fewer broker options in the first months, and keep the brokers who approved you early on a short list.
Booking Loads Without a Floor Rate
A load that looks good on gross revenue can lose money once empty miles, fuel and the truck’s fixed costs are counted. A carrier that books without a break-even rate can stay busy every week and still run out of money.
Skipping Compliance Requirements
Some new carriers delay UCR, IFTA setup or the testing consortium because enforcement feels distant. The new entrant audit comes within 12 months, and a missing drug and alcohol program or missing hours of service records is an automatic failure. Gaps also show up at roadside inspections and in the safety record brokers check during setup.
Realistic Timeline from Application to First Load
| Step | What happens | Timing |
|---|---|---|
| 1. Register the LLC and get an EIN | Entity filed, EIN issued, business bank account opened | Before you file; varies by state |
| 2. Quote insurance | Quotes at broker limits, $1,000,000 liability | Before you file |
| 3. Apply in Motus | USDOT number and operating authority, $300 for each type | Day 1 |
| 4. File the BOC-3 | Process agent named in each state | Right after the application |
| 5. Publication in the FMCSA Register | 10-day protest window opens | From the publication date |
| 6. Insurance filing | Insurer files proof of coverage with FMCSA | Within 20 days of publication |
| 7. Authority goes active | Carrier can haul under its own authority | Typically about 4 to 6 weeks from the application when steps overlap |
| 8. Broker setups | W-9, COI naming each broker, onboarding platforms | From activation onward; many brokers want some authority age |
| 9. First load (worked example) | Booked week 3, delivered week 4 | Counted from activation |
| 10. First payment (worked example) | Broker pays on 30 to 45 day terms | Around week 8 to 10 |
Overlapping the steps is what keeps activation near 4 to 6 weeks. Quoting insurance before you file and filing the BOC-3 right after the application are the 2 overlaps that matter most. A carrier that waits to shop for insurance until after publication works against the 20-day filing deadline.
Separate from this, if you factor your invoices or you’re about to, my free 16-video series walks through the real costs and the traps:
Frequently Asked Questions
How long does it take to start a trucking company?
When the steps overlap, active authority typically takes about 4 to 6 weeks from the Motus application. Done one after another, it takes longer. 2 fixed deadlines sit inside that window: a 10-day protest period after FMCSA publishes the application in the FMCSA Register, and 20 days from publication for your insurer to file proof of coverage. Quoting insurance before you file and filing the BOC-3 right after the application keep the process near the short end. After the authority goes active, broker setups add time before the first load, and the first broker payment commonly arrives 30 to 45 days after delivery.
How much does it cost to start a trucking company?
The fixed federal fee is $300 for each type of operating authority, and it is non-refundable. UCR for 0 to 2 vehicles is $46 for 2026 and $55 for 2027. Form 2290 runs up to $550 a year for a truck over 75,000 pounds. IRP plates vary by state and truck weight. Insurance is the largest cost after the truck: on a new authority it often runs $20,000 or more a year, with $1,000,000 in primary liability alone about $10,000 or more. None of this includes the truck, and the business also needs cash to carry its costs until the first broker payment arrives.
Can new trucking companies get loads immediately?
A carrier can legally book a load the day its authority goes active. In practice, many brokers want the authority to have some age before they load a carrier, and since the Supreme Court’s May 2026 ruling in Montgomery v. Caribe Transport II, brokers vet carriers harder. Load boards are the usual source of early freight. On each call, ask whether the broker works with new authorities, and have a W-9 ready along with an insurance agent who can issue a certificate naming the broker. In the worked example in this guide, the first load is booked in week 3 after the authority goes active.
Do I need both a DOT number and an MC number?
Any carrier running commercial vehicles in interstate commerce needs a USDOT number. A carrier hauling freight for hire across state lines also needs operating authority, identified by the MC number. A private carrier hauling its own goods may need only the USDOT number. Both are applied for through FMCSA’s Motus system. FMCSA may phase out MC numbers and identify carriers by USDOT number alone, but no date has been set. Until a change takes effect, brokers and onboarding platforms still ask for the MC number, so keep it on your setup documents and invoices.
What replaced the Unified Registration System?
FMCSA replaced the Unified Registration System with Motus in 2026. New carriers now apply for a USDOT number and operating authority through Motus. The deadlines that follow publication in the FMCSA Register still apply: a 10-day protest window, and 20 days from publication for the insurer to file proof of coverage, with the application dismissed unless you comply within 60 days if that filing is missed. If a checklist, course or video walks you through URS screens, it was made before the change. Use FMCSA’s current pages as the reference for each step.
Conclusion
Starting a trucking company follows a fixed order: entity, Motus application, BOC-3, insurance filing within 20 days of publication, active authority, broker setup, first load, first payment. Each step waits on the one before it, and a delay early in the chain moves the first payment back with it.
The carriers who reach their first broker payment with cash left had insurance quoted before they filed, the BOC-3 in early, a floor rate worked out before the first broker call, and a reserve sized to carry the business to around week 8 to 10. The filings take a few weeks. The wait for the first payment adds about 2 months on top of them, and that wait needs the most planning.

Leave A Comment